United Kingdom · New-build & resale
London property for sale: new-build apartments, off-plan and resale homes in the UK
Houses and apartments for sale in London for overseas buyers, from Nine Elms to Kensington, with stamp duty surcharges explained.
Property for sale in the UK draws overseas investors, families relocating to London and buyers diversifying across markets, and for most international buyers UK real estate means London. There are two routes in: new-build or off-plan, such as London new build apartments bought from a developer before completion, or resale, buying an existing house or flat from its owner through a solicitor or licensed conveyancer.
The rule that shapes the budget is Stamp Duty Land Tax (SDLT). Foreign individuals face no restrictions on owning UK homes, but in England and Northern Ireland a buyer who was not in the UK for at least 183 days in the 12 months before purchase pays a 2% surcharge, in force since 1 April 2021. If they will own another home anywhere, the 5% higher rates for additional dwellings (raised from 3% on 31 October 2024) also apply, reaching a combined 19% on the slice above GBP 1.5 million.
Natalie advises international buyers who want to buy property in the UK or invest in UK property alongside Dubai and other markets. She can walk through the difference between a new-build and a resale purchase in London, the tax points to raise with a UK solicitor, and will come back with what is available on request. That includes how the SDLT surcharges apply to a buyer's own situation, and which warranty and consumer code cover a new-build scheme.
Can foreigners buy property in the UK?
Yes. There are no restrictions on foreign individuals owning residential property in the UK. Overseas buyers are instead subject to extra tax and transparency rules, chiefly the SDLT surcharges in England and Northern Ireland: 2% for non-residents and 5% for buyers who will own more than one home, wherever the other home is.
Buying through an overseas company adds a further layer. The company must first register on the Register of Overseas Entities at Companies House, disclose its beneficial owners, obtain an Overseas Entity ID and update the register every year; HM Land Registry will not register it as owner without a valid ID (Economic Crime (Transparency and Enforcement) Act 2022). Companies also pay the higher SDLT rates and, for homes worth over GBP 500,000, the Annual Tax on Enveloped Dwellings.
Off-plan
Off-plan and new-build property in the UK
Off-plan property in the UK, including most London new build apartments, is sold by developers with a structural warranty and under a consumer code. There is no VAT for the buyer on a new home: new-build and resale homes pay SDLT at the same rates, on completion.
- Warranties such as NHBC Buildmark protect against loss of deposit, or extra cost to complete, if the builder becomes insolvent before completion, then provide a two-year builder warranty period and eight years of insurance cover for defects.
- Builders registered with the New Homes Quality Board must follow the New Homes Quality Code, which requires deposits to be protected, bans high-pressure selling and gives buyers access to the New Homes Ombudsman Service.
- Version 2 of the New Homes Quality Code applies to homes reserved on or after 2 March 2026 and adds a five-year affordability schedule of expected ownership and management costs.
- Registration with the New Homes Quality Board is not mandatory, and other builders follow codes such as the Consumer Code for Home Builders.
- Under the Consumer Code for Home Builders, a reservation fee must be refunded if you withdraw within the 14-day cooling-off period, less reasonable costs disclosed in advance.
Secondary market
Resale property in the UK
In England a resale purchase is handled by a solicitor or licensed conveyancer, with no notary stage. Contracts are exchanged with a deposit, commonly 10% of the price, and the sale completes later, when the balance is paid and the transfer is registered at HM Land Registry.
- The SDLT return must be filed and the tax paid within 14 days of completion, normally by your conveyancer.
- Many London flats are leasehold, so check the ground rent and service charges.
- A draft Commonhold and Leasehold Reform Bill, published on 27 January 2026, proposes capping existing ground rents at GBP 250 a year, but it is still in pre-legislative scrutiny and not law.
- Prime resale areas such as Westminster and Kensington and Chelsea hold the largest numbers of overseas-company-owned titles in London.
- Non-residents who later sell UK residential property must report and pay any Capital Gains Tax within 60 days of completion.
Off-plan or resale in United Kingdom?
| Off-plan | Resale (secondary) | |
|---|---|---|
| Deposit and payments | Reservation fee, refundable within the 14-day cooling-off period under the Consumer Code, then the contract deposit. | Deposit at exchange, commonly 10%, with the balance at completion. |
| Buyer protection | Structural warranty deposit cover and consumer code deposit protection. | Conveyancer's title and lease checks before exchange. |
| Purchase tax | SDLT at the same rates as resale; no VAT for the buyer. | SDLT, including any 2% non-resident and 5% additional-dwelling surcharges. |
| Timing to keys | At completion once the home is built. | At completion after exchange. |
| What you can inspect | Plans, the warranty and, for reservations from 2 March 2026 under the NHQB code, a five-year cost schedule. | The finished home, the title and, for flats, the lease. |
| Financing | Mortgages for non-residents come mainly from specialist and expat lenders. | Non-resident loan-to-value is commonly capped around 60-75%, a market norm rather than a rule. |
Buying costs in United Kingdom
- SDLT standard rates (from 1 April 2025)
- 0% up to GBP 125,000; 2% on GBP 125,001-250,000; 5% on GBP 250,001-925,000; 10% on GBP 925,001-1.5 million; 12% above GBP 1.5 million.
- Higher rates for additional dwellings
- 5 percentage points on top of standard rates for transactions from 31 October 2024 (up from 3%), so 5% / 7% / 10% / 15% / 17% across the bands.
- Non-resident surcharge
- An extra 2 percentage points for buyers not in the UK for at least 183 days in the 12 months before purchase, since 1 April 2021. Combined with the higher rates, up to 19% on the slice above GBP 1.5 million; a refund can be claimed if the 183-day test is met within the following year.
- First-time buyer relief
- 0% up to GBP 300,000 and 5% on GBP 300,001-500,000; no relief if the price exceeds GBP 500,000.
- Company purchases
- Higher rates apply to residential property of GBP 40,000 or more, and a 17% flat rate may apply to corporate purchases over GBP 500,000. ATED for 2026/27 runs from GBP 4,600 (GBP 0.5-1m) up to GBP 303,450 (over GBP 20m).
- High Value Council Tax Surcharge (planned)
- Planned from April 2028, not yet in force: GBP 2,500 to GBP 7,500 a year on homes in England worth GBP 2 million or more. Its design was consulted on from 19 May to 14 July 2026.
SDLT rates shown apply in England and Northern Ireland; confirm the rules for property in Scotland or Wales with your solicitor.
Residency through property in the UK
There is no residency route through property in the UK. Buying a home confers no immigration status, and the Tier 1 (Investor) visa, the former investment-based route, closed to new applicants on 17 February 2022.
For buyers who do move to the UK on another basis, the remittance basis for non-domiciled individuals was abolished from 6 April 2025 and replaced by a four-year foreign income and gains regime for new arrivals after 10 years of non-residence.
Where buyers look in United Kingdom
New developments and off-plan
- Nine Elms and Battersea Power StationLarge riverside regeneration zone in Wandsworth and Lambeth with substantial new-build apartment supply.
- Canary Wharf and Wood WharfDocklands business district with high-rise residential schemes.
- King's CrossRegenerated former railway lands with new apartments north of central London.
- White CityWest London regeneration around the former BBC Television Centre site.
- Greenwich Peninsula and Royal DocksEast London regeneration areas with large-scale new-build schemes.
- Earls CourtMajor redevelopment site in west London in planning and early delivery.
Established resale markets
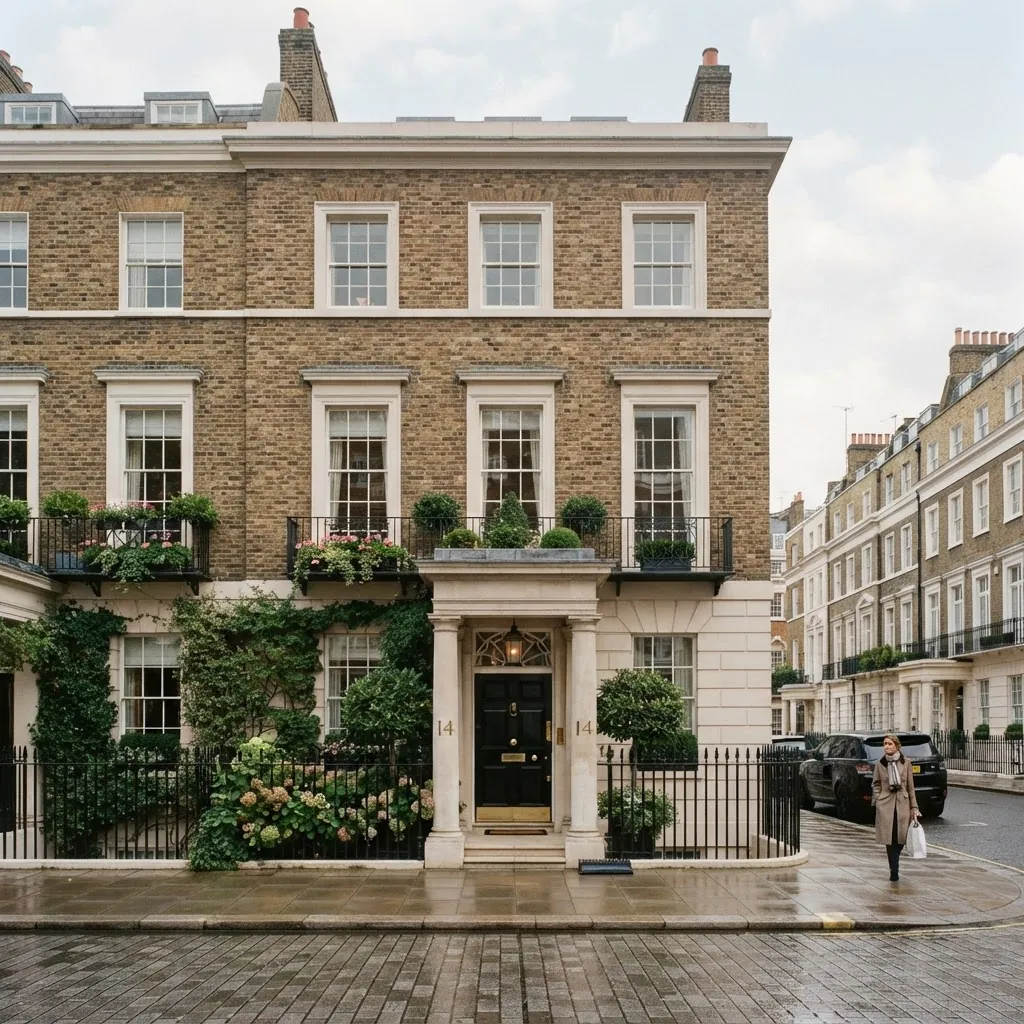
- Westminster (Mayfair, Belgravia, Marylebone)Prime central London; the borough with the most overseas-company-owned titles.
- Kensington and ChelseaPrime borough with deep stock of period houses and mansion flats.
- Notting Hill and Holland ParkEstablished residential areas with period houses.
- Hampstead and St John's WoodNorth-west London areas with large family houses and flats.
- Fulham and Chelsea HarbourResale terraced houses and riverside flats in south-west London.
- Islington and HighburyGeorgian and Victorian housing stock in north London.
The market in numbers
- ONS: average London house prices fell 3.3% in the 12 months to July 2026, the eleventh consecutive month of annual falls, to GBP 569,000, about GBP 19,000 below the July 2025 peak. UK prices rose 1.4% to GBP 273,000 over the same period.
- ONS: London private rents rose 3.5% in the 12 months to August 2026.
- HM Land Registry data, as reported in September 2026: 91,136 property titles in England and Wales are held by overseas companies, including 9,666 in Westminster (24.7% of the London total) and 4,958 in Kensington and Chelsea (12.7%).
What to watch for
- Combined SDLT for a non-resident buying an additional home is high, reaching 19% on the portion above GBP 1.5 million.
- London prices fell year on year for eleven consecutive months to July 2026, and capital values can go down as well as up.
- Homes in England worth GBP 2 million or more face a planned annual surcharge from April 2028, on top of council tax.
- Leasehold flats carry ground rent and service charges, and reform is proposed but not yet law, with uncertain timing.
- Buying through a company triggers ATED, higher SDLT and the Register of Overseas Entities regime, with penalties for non-compliance.
Buying property in United Kingdom: questions buyers ask
Can foreigners buy property in the UK?
Yes. There are no restrictions on foreign individuals owning UK homes, but non-residents pay a 2% SDLT surcharge in England and Northern Ireland, and overseas companies must register on the Register of Overseas Entities.
How much stamp duty does a non-UK resident pay?
Standard SDLT rates plus 2% if you were not in the UK for at least 183 days in the 12 months before buying. If you will own another home anywhere, the 5% higher rates also apply, up to 19% on the slice above GBP 1.5 million.
Should I buy off-plan, new-build or resale property in London?
Off-plan and new-build homes come with a structural warranty and consumer code deposit protection, and the same SDLT as resale. Resale lets you inspect the finished home and its lease or title before exchange.
Is my deposit safe when buying a new-build flat off-plan?
Warranties such as NHBC Buildmark cover loss of deposit if the builder becomes insolvent before completion, and the consumer codes require deposits to be protected. Check which warranty and code apply before reserving.
Can buying a London property give me a UK visa?
No. Property ownership confers no immigration status, and the Tier 1 (Investor) visa closed to new applicants in February 2022.
What is the 'mansion tax'?
It is the planned High Value Council Tax Surcharge: an annual charge from April 2028 of GBP 2,500 to GBP 7,500 on homes in England worth GBP 2 million or more. It is planned, not yet in force.
Sources
- GOV.UK: SDLT residential rates
- GOV.UK: SDLT on additional properties
- GOV.UK: SDLT for non-UK residents
- GOV.UK: High Value Council Tax Surcharge
- GOV.UK: ATED basics
- Estate Agent Today: overseas company ownership
- HM Land Registry: overseas entities (PG78)
- GOV.UK: Tier 1 Investor visa closure
- GOV.UK: non-dom tax changes
- ONS: private rent and house prices, September 2026
- NHBC: Buildmark cover
- NHBC: consumer codes
- Brodies: New Homes Quality Code v2
- Norton Rose Fulbright: draft leasehold bill
This page is general information, not legal, tax or financial advice. Rules and fees were checked against the sources above in October 2026 and can change.
BEGIN YOUR JOURNEY
No public listings in United Kingdom right now
Opportunities in United Kingdom are shared privately. Tell Natalie what you are looking for, off-plan or resale, and she will come back with what is available.
SCHEDULE A DIALOGUE →Other markets Natalie advises on
- Property in Dubai
- Property in Abu Dhabi
- Property in Ras Al Khaimah
- Property in Qatar
- Property in Oman
- Property in Saudi Arabia
- Property in Egypt
- Property in Spain
- Property in Portugal
- Property in Greece
- Property in Switzerland
- Property in Georgia (Tbilisi and Batumi)
- Property in Bali
- Property in Zanzibar
- Property in the Maldives